


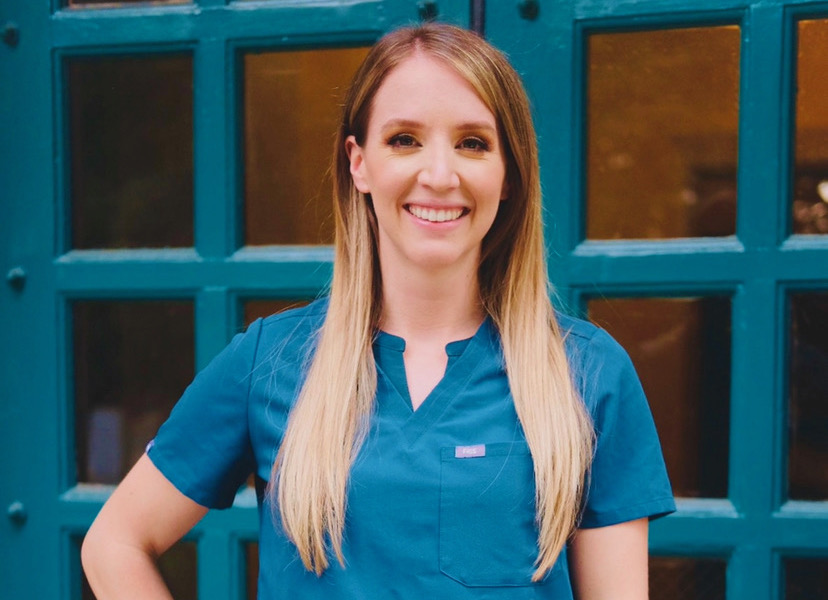
Brittany Vacura, D.D.S., is a normal dentist and dental director for a federally certified well being heart in Sacramento, California. She graduated from the College of California San Francisco College of Dentistry in 2017 and the College of Nevada Las Vegas College of Dental Drugs normal apply residency in 2018. Dr. Vacura enjoys encouraging dental scholars and co-workers to take rate in their price range. Through the years, she hopes to recruit and mentor extra new dentists into the profession of neighborhood dentistry.
As new dentists, we will be able to all understand that gut-wrenching second once we won an e-mail from our mortgage servicer caution us that our bills could be due quickly. Taking a look again at our time as dental scholars, we spent years studying the intricacies of prepping essentially the most ideally suited elegance II recovery, administering anesthetic and memorizing mnemonics so as to cross our board assessments. Seldom did we discover ourselves calculating our web price or figuring out which mortgage compensation means would paintings easiest for us. Realistically, when would we’ve had the time? That is one thing many people should navigate on our personal as a result of there is not any formal coaching in dental college.
No longer lengthy after graduating, many people in finding ourselves in need of to get married, purchase a space, purchase a automotive, purchase a tradition, have youngsters or get started making an investment for retirement. The ones first few years can really feel like being stretched in such a lot of other instructions. Irrespective of the place lifestyles takes you, it’s necessary to have a plan early on. Time can paintings in our prefer however too can paintings towards us.
The ADA is advocating for dozens of scholar mortgage reforms that might lend a hand mitigate those monetary burdens, and choices are to be had now for brand spanking new dentists in search of debt aid. It wasn’t till my grace duration that I changed into crushed with the considered six-figure scholar mortgage debt. I began to do intensive analysis on other compensation plans and philosophies. Here’s a abstract of what I’ve realized thru my mortgage compensation adventure.
Reimbursement plans
Reimbursement plans may also be oversimplified into the next 3 classes:
1. Fastened-payment compensation plans: The ones with federal loans can benefit from a fixed-payment compensation plan, reminiscent of the usual compensation plan, which divides your overall mortgage debt over 10 years (120 equivalent bills). Since the per 30 days bills may also be top, I don’t suggest same old compensation plans for individuals who have greater than $200,000 in scholar mortgage debt.
2. Source of revenue-driven compensation plans: The ones with federal loans can sign up in an income-driven compensation plan. The latest is known as the Saving on a Precious Training plan, which changed the Revised Pay As You Earn plan in 2023. This compensation plan calculates your per 30 days bills via taking 10% of your annual discretionary revenue and dividing it into 12 equivalent bills. This plan not calls for you to incorporate spousal revenue and takes your circle of relatives dimension into consideration when figuring out your per 30 days fee. Any amassed pastime that isn’t lined via your per 30 days fee is eradicated, which is a large receive advantages. After 25 years in this compensation plan, the remainder steadiness of your loans will likely be forgiven; on the other hand, the quantity forgiven qualifies as taxable revenue. This compensation possibility can receive advantages new grads proper out of faculty as it provides the versatility of low per 30 days bills when your revenue is inconsistent or less than expected.
3. Non-public consolidation: You’ll additionally refinance your loans thru a non-public mortgage servicer for a decrease rate of interest, however this generally calls for the loans to be repaid over a shorter time period, reminiscent of 3 to 5 years. Even if federal compensation plans generally tend to have upper rates of interest, they provide extra flexibility on the subject of when debtors are not able to make bills or need to alternate compensation plans. It’s necessary to know non-public loans aren’t eligible for federal mortgage compensation or public carrier mortgage forgiveness.
The right way to strategize
When opting for a federal compensation plan, there’s no want to pressure. You’ll technically alternate your thoughts and turn between compensation plans (even if this isn’t advisable as a result of every time you reapply, your pastime is compounded).
Regardless of how a lot scholar mortgage debt you may have, many new dentists will have the benefit of enrolling within the income-driven compensation plan SAVE. The primary few years of training dentistry are anxious sufficient, and nobody needs to fret about having sufficient cash to hide their mortgage bills. Source of revenue-driven compensation plans will let you alter or pause your bills when your revenue decreases otherwise you change into unemployed.
Many new dentists with the aim of going into apply possession use SAVE to stay their mortgage compensation bills low whilst their preliminary apply bills are top. Dentists who apply section time or pass out on prolonged depart additionally use this compensation means since it’s without delay correlated to their revenue.
Even if the SAVE plan will forgive your overall steadiness after 25 years, many dentists will have the benefit of paying off their loans sooner than 25 years. Because of this having a plan early on is so necessary.
The function will have to be discovering the steadiness amongst repaying your loans in a cheap period of time, minimizing the pastime accruing and having the versatility to invest in different priorities.
Public Provider Mortgage Forgiveness and mortgage compensation techniques
There are methods to pay down your scholar mortgage debt the usage of the Public Provider Mortgage Forgiveness program and mortgage compensation techniques.
The PSLF program calls for you to be hired complete time via a U.S. federal, state, native or tribal executive or not-for-profit group. You should have federal loans and also you should be enrolled in an income-driven compensation plan, reminiscent of SAVE. The PSLF program will forgive your ultimate mortgage steadiness after 120 qualifying per 30 days bills. In contrast to the income-driven SAVE plan, the quantity forgiven beneath PSLF isn’t taxable.
There are lots of other state and federal mortgage compensation techniques by which dentists who paintings in executive or not-for-profit organizations can take part. Those techniques come with the ones subsidized via the Nationwide Well being Provider Corps and Indian Well being Provider and generally require a two- to three-year carrier dedication.
Even if you’ll be able to’t take part in a couple of mortgage compensation program on the similar time, what many dentists don’t know is that you’ll be able to take part in each PSLF and a mortgage compensation program on the similar time. Running for a neighborhood well being heart or college can stay per 30 days income-driven bills low. You’ll then use finances from a mortgage compensation program to make those per 30 days bills. You’ll additionally renew your mortgage compensation contracts till the full steadiness is paid in complete otherwise you whole 10 years of public carrier. Dentists who benefit from those techniques could have nearly all of their scholar loans paid for this manner.
For the ones in non-public apply who’re enrolled in SAVE, mortgage compensation methods require nearer attention. One should make a decision if taking part for 25 years for the forgiveness is well worth the corresponding taxes.
Actual-life packages
To higher conceptualize those mortgage compensation methods, I really like to make use of this situation of similar quadruplets. Annie, Bonnie, Connie and Donnie graduated from the similar dental college with $450,000 in scholar mortgage debt. Those new dentists have a beginning wage of $180,000 with an annual building up of three% in line with 12 months.
• Annie participates in the usual compensation plan at 5% pastime. She will pay $4,772 per thirty days for 10 years. The whole value of the mortgage after 10 years could be $572,754.
• Bonnie participates within the SAVE plan at 5% pastime. She will pay $1,117-$2,140 per thirty days for 25 years. The whole value of the mortgage after 25 years could be $409,223, with $449,686 forgiven. The volume forgiven is thought of as taxable revenue, so she would owe an extra $179,874 in taxes the 12 months her loans have been forgiven.
• Connie participates within the SAVE plan at 5% pastime, however she works for a nonprofit group and has enrolled in PSLF. She will pay $1,117-$1,457 per thirty days for 10 years. The whole value of her mortgage after 10 years could be $136,142, with $500,784 being forgiven tax loose.
• Donnie participates within the SAVE plan at 5% pastime, and she or he additionally works for a nonprofit group. She has enrolled in PSLF and participates within the Nationwide Well being Provider Corps Mortgage Reimbursement Program. Her per 30 days bills are $1,117-$1,457 per thirty days for 10 years. The whole value of her mortgage after 10 years could be $136,142, however since she used her NHSC disbursements to hide her per 30 days bills, she had no out-of-pocket bills, and $500,784 will likely be forgiven tax loose.
Phrases of encouragement
It’s necessary to understand that our scholar mortgage debt does no longer outline us. I imagine that being knowledgeable and conscious about your monetary scenario can come up with the equipment to reach your objectives and are living an intentional, significant lifestyles with out crippling scholar mortgage debt.
This data is for tutorial functions simplest and will have to no longer be thought to be monetary recommendation. The examples have been calculated the usage of studentloanplanner.com.


